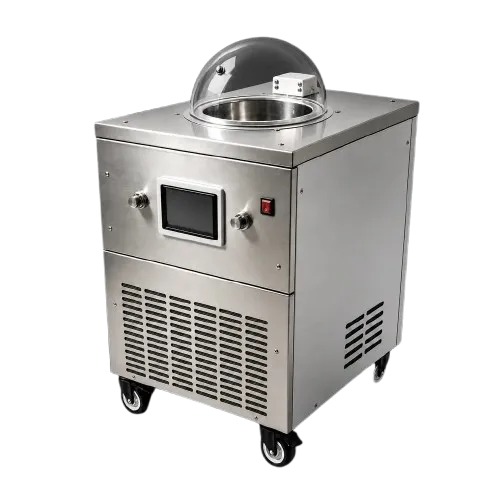
An ice cream machine is a capital asset, not an expense. That distinction decides how much of it hits your tax return in year one and how much is spread across the years you actually use it. The rules differ by country, but the structure is similar everywhere: classify the asset, choose a method, keep the records, and confirm the treatment with your accountant before you file.
This is a framework, not tax advice. Numbers below are illustrative.
The three levers
- Classification. Equipment used in a business is usually treated as a depreciable fixed asset. The class life — five, seven or ten years depending on the jurisdiction and the asset type — sets the default schedule.
- Method. Straight-line spreads the cost evenly over the class life. Accelerated methods front-load the deduction, and many countries offer first-year expensing or bonus depreciation for small businesses.
- Timing. When the asset is “placed in service” matters more than when you paid for it. A machine delivered in December but installed in January may fall into a different tax year.
A worked example (illustrative)
Machine cost US$5,000, class life seven years, straight-line, no salvage value. The annual deduction is about US$714. Under an accelerated or first-year expensing regime, the year-one deduction could be the full amount, subject to caps and eligibility. The difference in cash flow is real; the total deduction over the asset’s life is the same unless the rules change.
| Year | Straight-line | First-year expensing |
|---|---|---|
| 1 | $714 | up to $5,000 (if eligible) |
| 2–7 | $714 each | $0 |
| Total | $5,000 | $5,000 |
The accelerated path improves cash flow but removes future deductions. For a profitable shop, that is often worth it; for a shop with losses, it may waste the deduction.
What usually qualifies
- The machine itself, including the base unit and required accessories
- Installation costs that are capital in nature (electrical work, drainage modification)
- Freight and duties capitalised into the asset cost, depending on local rules
- Software or control upgrades bundled with the machine
What usually does not qualify as part of the machine: routine maintenance, consumables, and repairs that keep the asset in its existing condition. Those are expenses in the year incurred — which is why the maintenance budget and the capital budget should be tracked separately.
Records that survive an audit
- Purchase invoice and customs documents showing landed cost
- Installation invoice and date placed in service
- Serial number and asset register entry
- Depreciation schedule with method and class life
- Disposal record when you sell or scrap the machine
A machine without a placed-in-service date is a machine with a tax argument attached.
Lease vs buy, from a tax angle
Lease payments are usually deductible as operating expenses; a purchase creates a depreciable asset with possible interest deductions if financed. Which is better depends on your tax position, cash flow and whether you want to own the residual value. The financing guide covers the commercial comparison; your accountant covers the tax side.
Cross-border wrinkles
If you import the machine, the capitalised cost is usually the landed cost, not the FOB price — freight, duty and some clearance costs become part of the asset. Keep the import documents with the asset register: the shipping and import documents guide lists them, and the equipment budget guide shows where the machine sits in the overall capital plan.
VAT/GST is normally recoverable and not part of the depreciable cost if you are registered — confirm with your accountant, because treatment varies.
FAQ
Can I write off the whole machine in year one?
In some jurisdictions and for some businesses, yes — through first-year expensing or bonus depreciation, subject to caps and eligibility. In others, no: you follow the class life. The only safe answer is to check the rules where you file.
Does maintenance reduce the depreciable value?
No. Routine maintenance is an expense, not part of the asset cost. Capital improvements that extend life or capacity may be treated differently.
What if I buy used?
Used equipment is usually depreciable too, often over the same class life, though some jurisdictions apply different rules for used assets. Keep the purchase invoice and the placed-in-service date.
What happens when I sell or scrap it?
The difference between sale proceeds and the remaining book value is a gain or loss, treated under local rules. Record the disposal — an asset that disappears from the register without a disposal record invites questions.
If you are building the capital plan, tell us the machine and market — an export engineer replies within 24 hours with a landed-cost figure you can hand to your accountant. Request a landed-cost quote.
Sources: general depreciation practice (class life, straight-line vs accelerated methods, placed-in-service timing). This is not tax advice — confirm classification, method and eligibility with a qualified accountant in your jurisdiction.
Some information may be outdated
Comments
Questions about equipment capacity, voltage, or recipes? Leave a comment.
Loading comments...